
In short
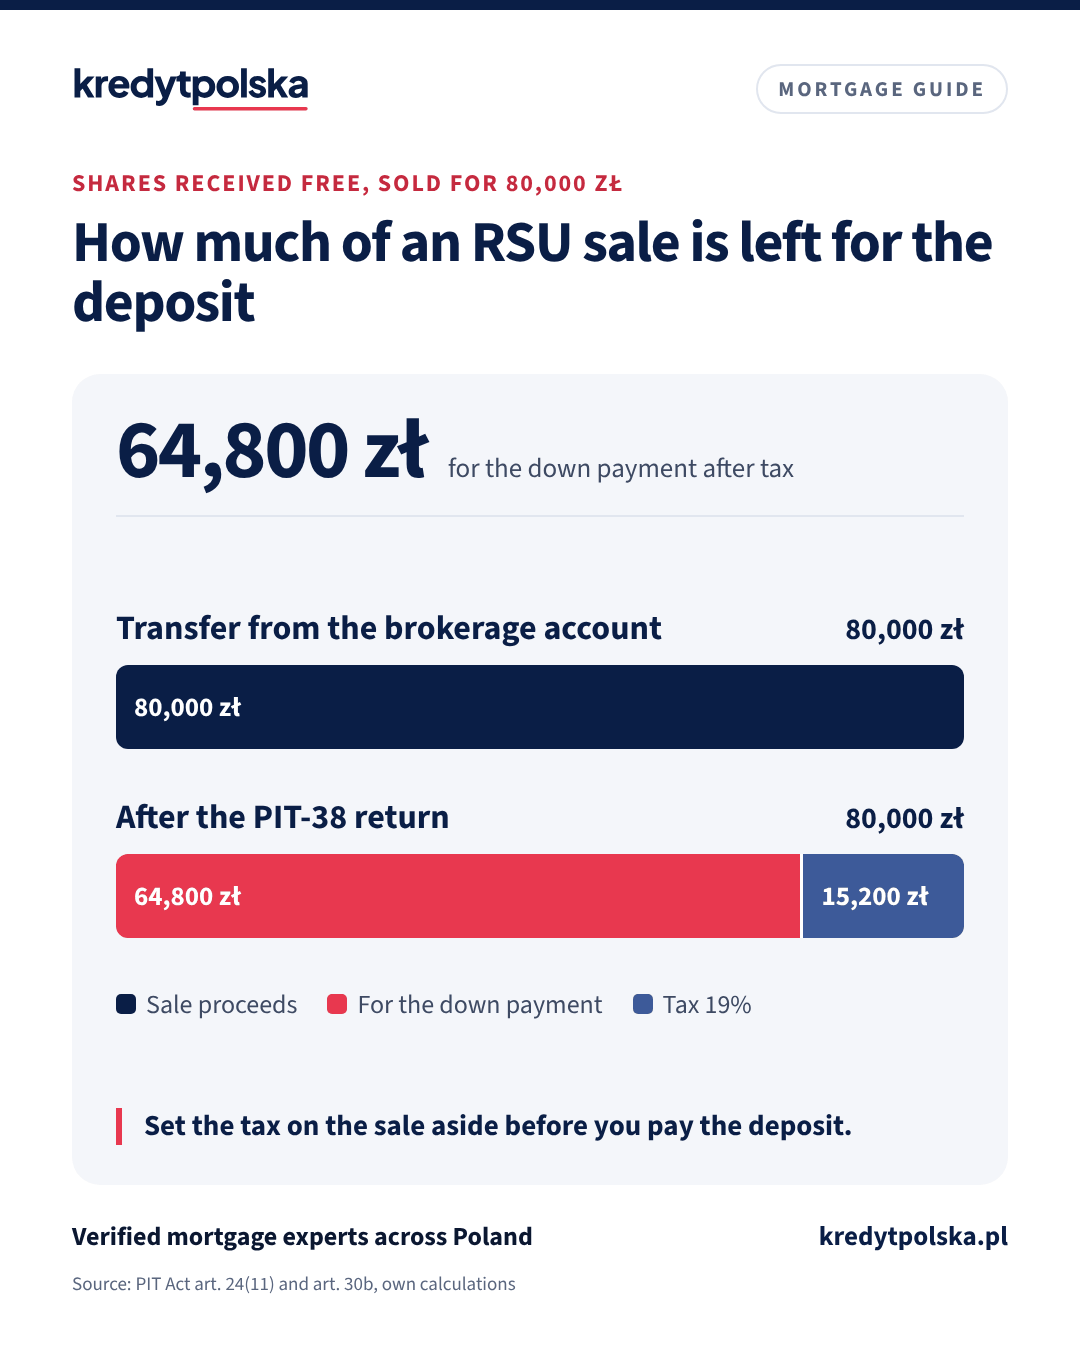
Shares from your employer (RSU, stock options, ESPP) can be your down payment only once they are yours, you sell them and the money reaches your account in złoty. Unvested RSUs and unexercised options are just a promise for a bank. Polish banks calculate borrowing capacity mainly from your salary and usually treat shares as a variable bonus or do not count them at all. If the plan meets the conditions of an incentive programme under the Polish PIT act, tax is due on sale: from free shares sold for 80,000 zł, 64,800 zł is left for the down payment.
Only vested shares count
An RSU becomes a share only on the vesting date, usually quarterly or yearly and only if you still work for the company. Until then a bank cannot accept it, because it is usually lost when you change jobs. Stock options give only a right to buy at a set price, and exercising them costs money. ESPP shares are bought with your own salary deductions, so they are yours from the purchase date.
| Type | When the shares are yours | For the down payment |
|---|---|---|
| RSU before vesting | not yet | no, it is only a promise |
| RSU after vesting | from the day they reach your account | yes, after the sale |
| Options before exercise | not yet | no |
| Options after exercise | after paying the exercise price | yes, after the sale |
| ESPP shares | from the purchase date | yes, after the sale |
The exact dates follow from your plan's rules.
Down payment: sell first
You pay the seller in złoty, so sell the shares and transfer the money to your account in Poland. The bank examines the source of funds (Polish anti-money laundering act, art. 34(1)(4)(b)). Prepare the grant agreement or plan rules, the broker statement with the sale, the transfer to your account and the PIT-38 return with confirmation (UPO) once the deadline has passed. Plans are often run by foreign brokers in dollars or euro, so count only the złoty amount that actually reached your account.
Do shares count as income?
Banks calculate capacity from stable, documented income. The number of tranches depends on staying with the company and their value on the share price, so most banks use the base salary only. Some may count regular tranches like a variable bonus if they are documented by the employer and repeat over a longer period. Ask the bank before you apply. Shares still help: a bigger down payment means a lower LTV and often a lower margin.
Tax
If the plan meets the conditions of an incentive programme in the Polish PIT act (created by a general meeting resolution of a joint-stock company, also a parent company based in the EU, EEA or a treaty country), no tax is due when you receive the shares. Income arises on sale and is taxed at 19% in PIT-38, due by 30 April of the following year; for free shares there is no acquisition cost, so the tax is on the whole sale amount. Foreign currency income is converted at the NBP average rate from the last working day before the sale. If the conditions are not met, income may arise already when you receive the shares.
The full description in Polish, with an example and a document checklist: Akcje pracownicze i RSU a kredyt hipoteczny.
Frequently asked questions
Can I use RSUs as a down payment in Poland?
Yes, once they have vested, you sell them and transfer the money to your account in złoty. The bank accepts the broker statement, the plan rules and the transfer confirmation.
Will a bank accept unvested RSUs?
Usually not. Until a tranche reaches your account you may lose it, for example when you change jobs, so it is neither a down payment nor secure income.
What tax do I pay when I sell RSU shares?
If the plan meets the conditions of an incentive programme under the Polish PIT act, 19% on sale in PIT-38, on the whole sale amount for free shares. Otherwise income may arise already when you receive the shares.
Sources
- Polish PIT act of 26 July 1991, art. 11a, 24(11)-(12a), 30b (Polish)
- Act of 1 March 2018 on counteracting money laundering and terrorist financing, art. 34 (Polish)
- KNF, Recommendation S (Polish)
This guide describes general rules and typical bank practice as of October 2026. Details
It is not legal or tax advice and not a bank offer. Each bank sets its own criteria, and the lending decision is always made by the bank.
Read next
Mortgage calculator for Poland: your monthly instalment
Mortgage calculator for foreigners buying in Poland: equal or decreasing instalments in złoty, total interest, LTV, the bank stress test and a year-by-year schedule.
Crypto and stock market money and a mortgage in Poland: down payment and income
Will a Polish bank accept money from cryptocurrencies, shares or ETFs as a down payment or as income? Source of funds checks (AML), 19% tax in PIT-38 and the documents to prepare.
Inherited money as a down payment in Poland: documents and inheritance tax
Can you use cash from an inheritance as a down payment in Poland? The court decision or notarial certificate, the SD-Z2 form within 6 months, inheritance tax for other relatives and what Polish banks ask for.
Mortgage for foreigners in Poland: what banks require in 2026
Can a foreigner get a mortgage in Poland? Residence card, PESEL, income, down payment and credit history: what Polish banks check and how the process works.
Employer social fund (ZFŚS) loan as a down payment: what a Polish bank says
Can a cheap housing loan from your employer’s company social benefits fund (ZFŚS) be your mortgage down payment in Poland? Recommendation S, how the bank sees it and how much capacity it costs.
Unregistered business activity in Poland: does the bank count this income for a mortgage?
How Polish banks treat income from unregistered business activity (działalność nierejestrowana) in a mortgage application, the 2026 limit and the documents to prepare.
Mortgage for content creators in Poland: how banks count income from YouTube, Instagram and TikTok
How Polish banks assess income of YouTubers, influencers and other online creators in a mortgage application: platform payouts, brand deals, barter, foreign currency and documents.