
In short
Unpaid leave does not rule out a mortgage, but during the leave there is no salary for the bank to count, and banks ask about it in the employment certificate. Even a short leave lowers your average income: with 7,000 zł net, one month without pay gives a 3-month average of 4,667 zł. The simplest options are to apply before the leave or after you return, once that month drops out of the average. While repaying, instalments continue as usual, so plan the leave with savings or ask the bank to change the repayment schedule.
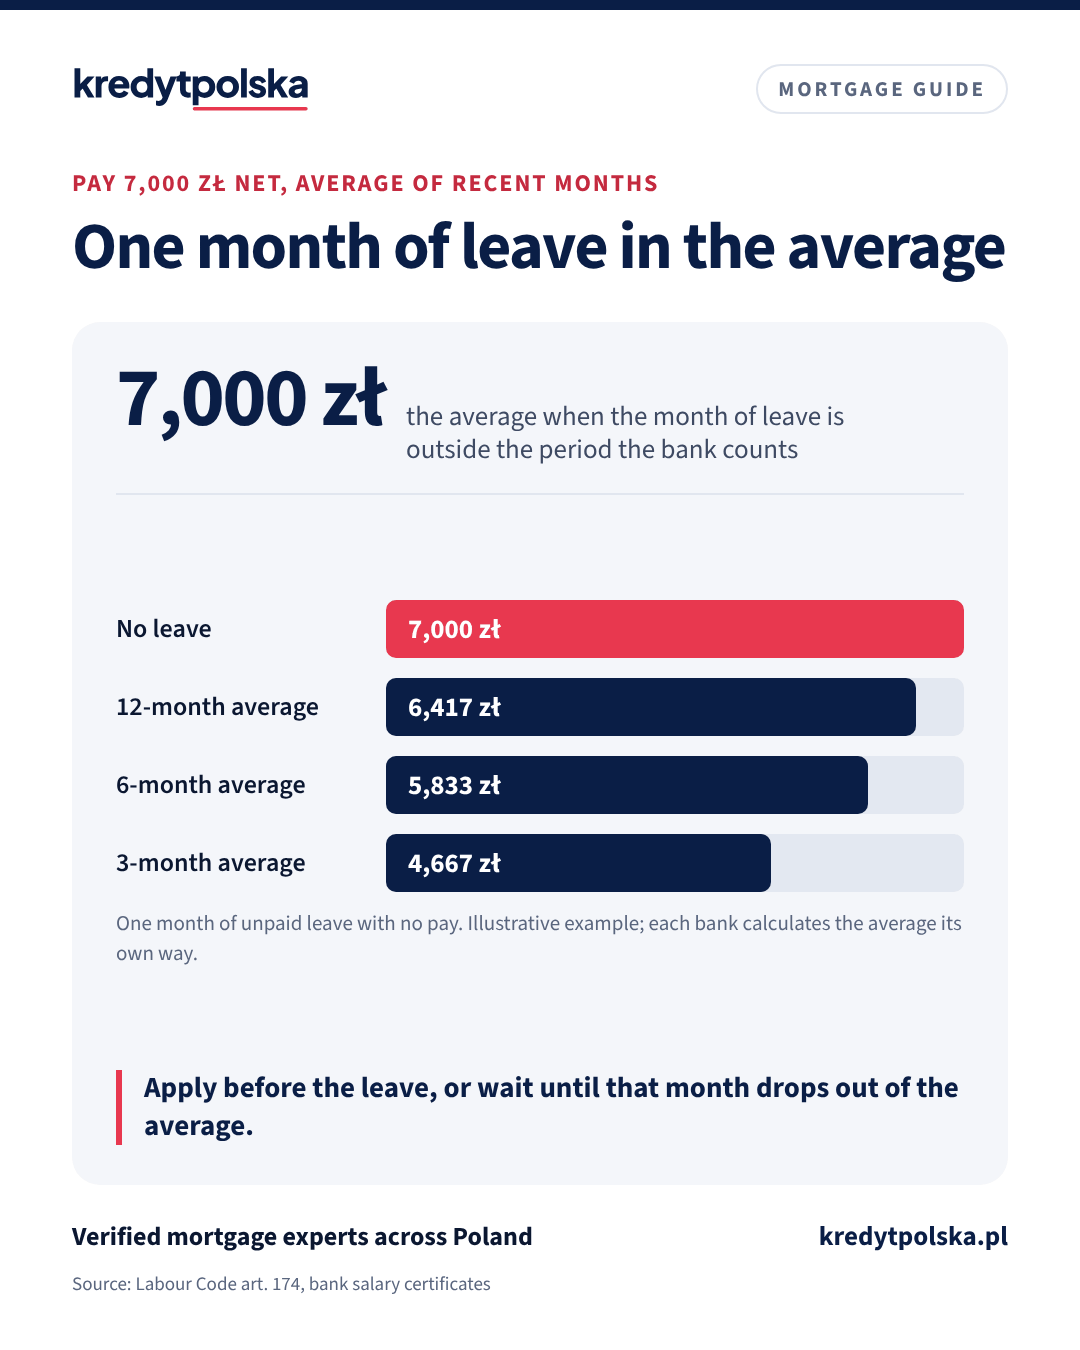
What unpaid leave changes
Under the Polish Labour Code (art. 174) unpaid leave is granted at your request and your employer may agree or refuse. Your employment contract continues, but there is no salary. The period does not count towards the length of service on which employee rights depend, unless the leave is to work for another employer under an agreement between the two employers (art. 174¹). Health insurance cover (NFZ) ends 30 days after the leave begins unless you insure yourself voluntarily or as a family member, and no sickness benefit is paid for illness during the leave.
Before and during the application
Banks usually take your average net salary from the last 3, 6 or 12 months. A month of unpaid leave counts as zero: with 7,000 zł net it lowers the average to 5,833 zł over six months and 4,667 zł over three. Many banks ask directly on their employment certificate form whether you are on unpaid leave. If you are on leave when the certificate is issued, the bank usually has no current income to count, so you can apply before the leave, wait until you are back at work, or base the application on a co-borrower's income. Do not hide the leave: your employer states it on the certificate anyway.
Between the decision and the payout
Before you sign and before the money is paid out, the bank asks you to confirm that nothing has changed, and sometimes for a new certificate, as the old one is valid only for a limited time. If your leave starts in that period, tell the bank before the payout. It is safer to plan the leave after the whole loan has been paid out, and for a house build after the last tranche.
While repaying the mortgage
Unpaid leave does not change your loan agreement: instalments are due as before. Check how many instalments your savings cover, whether your agreement links a margin discount to regular salary payments into the account, and whether you must inform the bank about a change in income. Job-loss insurance usually does not cover unpaid leave, because your job continues. If repayments may be difficult, talk to the bank before the leave: the Mortgage Credit Act (art. 33) lists restructuring options such as suspending repayments, changing instalments or extending the loan term, and the bank decides after assessing your situation. There are no statutory payment holidays in 2026. When you return to work, your borrowing capacity returns with your salary.
The full description in Polish: Urlop bezpłatny a kredyt hipoteczny.
Frequently asked questions
Can I get a mortgage in Poland while on unpaid leave?
Usually not on your own income, because there is no salary during the leave and banks ask about it on the employment certificate. It is possible with a co-borrower whose income the bank can count, or after you return to work.
Does a short unpaid leave a few months ago matter?
It can lower your average income. With 7,000 zł net, one month without pay gives an average of 4,667 zł over three months and 5,833 zł over six. Some banks count full months only, others use the average.
Will the bank suspend my instalments during unpaid leave?
Not automatically. You can apply for restructuring, for example a suspension of repayments or a longer loan term, and the bank decides after assessing your situation. There are no statutory payment holidays in 2026.
Sources
- Labour Code, art. 174 and 174¹, consolidated text Journal of Laws 2025 item 277 (Polish)
- Act on publicly funded health care, art. 69(3), consolidated text Journal of Laws 2025 item 1461 (Polish)
- Zielona Linia (gov.pl): unpaid leave and health and sickness insurance (Polish)
- Mortgage Credit Act, art. 33 (Polish)
This guide describes general rules and typical bank practice as of October 2026. Details
It is not legal or tax advice and not a bank offer. Each bank sets its own criteria, and the lending decision is always made by the bank.
Read next
Mortgage calculator for Poland: your monthly instalment
Mortgage calculator for foreigners buying in Poland: equal or decreasing instalments in złoty, total interest, LTV, the bank stress test and a year-by-year schedule.
Working in a family business in Poland: how banks treat a salary from a parent or spouse
How Polish banks assess a mortgage application when your employer is your parent or spouse, what the Polish social insurance rules on “cooperating persons” mean, and which documents help.
Moving abroad while repaying a Polish mortgage: the bank, insurance and the instalment
You are moving abroad and still repaying a mortgage in Poland. Can the bank terminate the loan, how to pay the instalment from a salary in euro, insurance, renting out the flat, tax and the 2% loan subsidies.
Foster family or adoption and a mortgage in Poland: what the bank counts
Can a foster family get a mortgage in Poland? How banks treat the pay of a professional foster family, the child allowance and the 800 zł supplement, how a child affects capacity and what adoption changes in the RKM programme.
Mortgage with commission-based pay in Poland: how banks count sales commission
How Polish banks count commission (prowizja) of sales representatives and agents in a mortgage application: base salary, average commission, agency contracts and documents.
Mortgage in Poland when you work remotely for a foreign company: employment contract or B2B
You live in Poland and work from home for a company abroad, on an employment contract or as a B2B contractor: how Polish banks treat this income, what the salary currency changes, tax, social security and documents.
Buying your municipal flat in Poland: discount, payment by instalments or a mortgage
How to buy a municipal flat from the gmina in Poland: the tenant's priority right, the discount set by the municipal council, instalments from the gmina for up to 10 years or a bank loan, and when the discount must be repaid after a sale within 5 years.