
In short
Many Polish banks count income from renting out rooms, provided you have a written agreement with each tenant, rent has reached your account for usually 6–12 months and you pay the flat-rate tax. Room rental brings more revenue than letting the whole flat, but some banks deduct the bills you pay for tenants and use an average that includes empty months. Rent from rooms in a flat you are only buying is usually not counted.
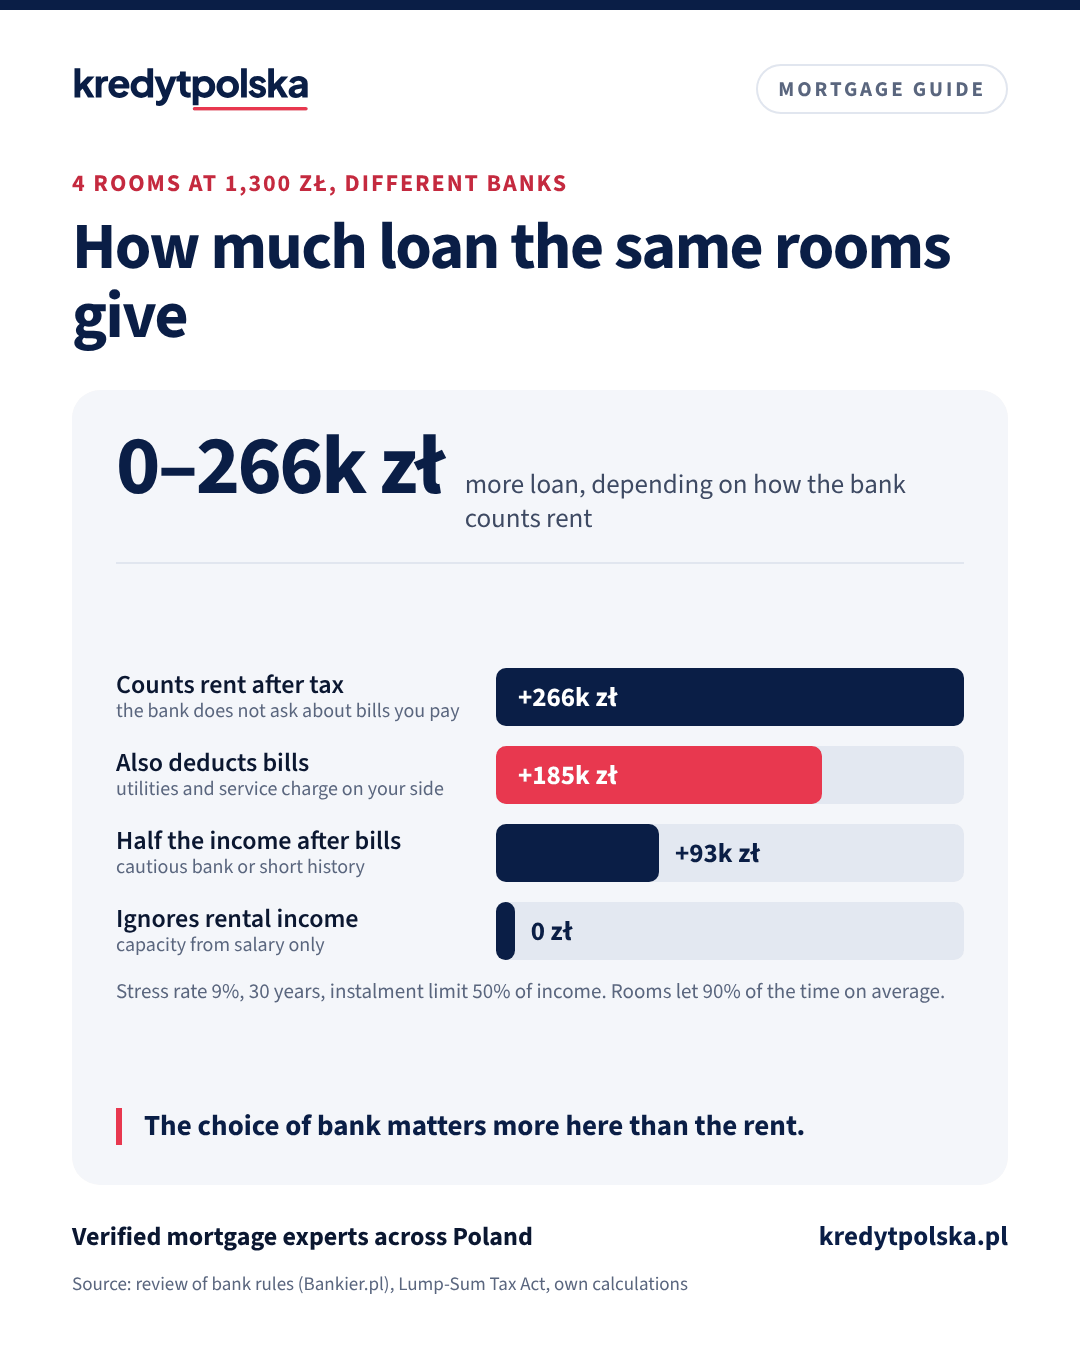
Does the bank count income from rooms
In many banks, yes. For a Polish bank, renting out rooms is still rental income, assessed like rent for a whole flat: written agreements, rent paid by bank transfer, usually 6–12 months of history, and the flat-rate tax (ryczałt) declared on the PIT-28 return. Some banks allow tenants to change during that period if payments were continuous. Others do not count rental income at all or treat it only as additional income.
| How the bank counts rent | Income counted | More loan |
|---|---|---|
| Counts rent after tax the bank does not ask about bills you pay | 4,282 zł | +266,000 zł |
| Also deducts bills utilities and service charge on your side | 2,982 zł | +185,000 zł |
| Half the income after bills cautious bank or short history | 1,491 zł | +93,000 zł |
| Ignores rental income capacity from salary only | 0 zł | 0 zł |
Assumptions and sources. Details
Model example, not a bank offer: 4 rooms at 1,300 zł, let 90% of the time, 8.5% lump-sum tax, 1,300 zł a month of service charge, utilities and internet on your side.
Bills included in the rent
Room tenants usually pay one amount that includes utilities and internet. Some banks deduct the costs paid by the owner, such as utilities and the building service charge, and count only what is left. In our Polish example 4 rooms at 1,300 zł bring about 4,680 zł a month on average, but after the 8.5% tax and 1,300 zł of bills only about 2,982 zł remains. Depending on the bank, the same rooms can add nothing or around 266,000 zł to the amount you can borrow.
Buying a flat to rent out rooms
Banks usually do not count future rent from a flat you are buying, because there are no agreements or payments yet. Your current income has to cover the loan, and the instalment should still be affordable when some rooms are empty. Such a flat is bought with a standard mortgage, usually with a deposit of at least 20%, and without government programmes for buyers meeting their own housing needs.
Converting a flat and tax
An extra room rarely raises the bank valuation, and under Polish building rules a room for people must have daylight, so a room without a window is not a room. Long-term room rental without services is usually private rental taxed at 8.5% of revenue up to 100,000 zł a year. Nightly lets with cleaning and fresh linen may be treated as a business.
The full description in Polish, with tables and a checklist of documents: Mieszkanie pod wynajem pokoi: czy bank uzna taki dochód.
Frequently asked questions
Will a Polish bank count income from renting out rooms?
Many banks will, on the rules for rental income: written agreements with tenants, rent on your account for usually 6–12 months and the flat-rate tax paid. Some banks do not count rental income at all.
Will the bank deduct the bills I pay for room tenants?
Some banks do. They take the average rent minus utilities and other costs paid by the owner, which can reduce the counted income considerably.
Is renting out rooms a business in Poland?
Long-term room rental without extra services is usually private rental taxed at 8.5%. Nightly lets with cleaning and linen changes may be treated as a business.
Sources
- Bankier.pl: rental income and mortgage capacity, bank survey 2018 (Polish)
- Flat-rate income tax act of 20 November 1998 (ISAP, Polish)
- Tax ruling on renting out 8 rooms, 2017 (podatki.biz, Polish)
- Technical conditions for buildings, § 57 (ISAP, Polish)
This guide describes general rules and typical bank practice as of October 2026. Details
It is not legal or tax advice and not a bank offer. Each bank sets its own criteria, and the lending decision is always made by the bank.
Read next
Mortgage calculator for Poland: your monthly instalment
Mortgage calculator for foreigners buying in Poland: equal or decreasing instalments in złoty, total interest, LTV, the bank stress test and a year-by-year schedule.
Unregistered business activity in Poland: does the bank count this income for a mortgage?
How Polish banks treat income from unregistered business activity (działalność nierejestrowana) in a mortgage application, the 2026 limit and the documents to prepare.
Foreign pension and a mortgage in Poland: does the bank count a German or other EU pension?
How Polish banks treat a pension from Germany or another EU country in a mortgage application: currency conversion, documents from the foreign pension office, tax and pensions from two countries.
Mortgage for a condo hotel or investment apartment in Poland: will a bank lend and on what terms?
Can you get a Polish mortgage for a unit in a condo hotel or aparthotel? Commercial unit vs flat, deposit, VAT 23% and its refund, the operator agreement and what the developer act does not cover.
Mortgage when working part-time in Poland: will a bank lend and how much?
Can you get a Polish mortgage on a part-time job (pół etatu)? How banks count part-time pay, an example for full-time, 3/4 and half-time, reduced hours after parental leave and what raises the amount.
Bonuses, overtime and shift pay: how much does a Polish bank count?
How Polish banks treat monthly, quarterly and annual bonuses, the 13th salary, overtime and shift or night allowances when they calculate borrowing capacity, and how to document them.
Mortgage in Poland on a management contract or a board appointment: how banks count your income
How Polish banks assess income from a management contract (kontrakt menedżerski) or a board appointment (powołanie): tax form, term and dismissal, invoicing through your own company and documents.