
In short
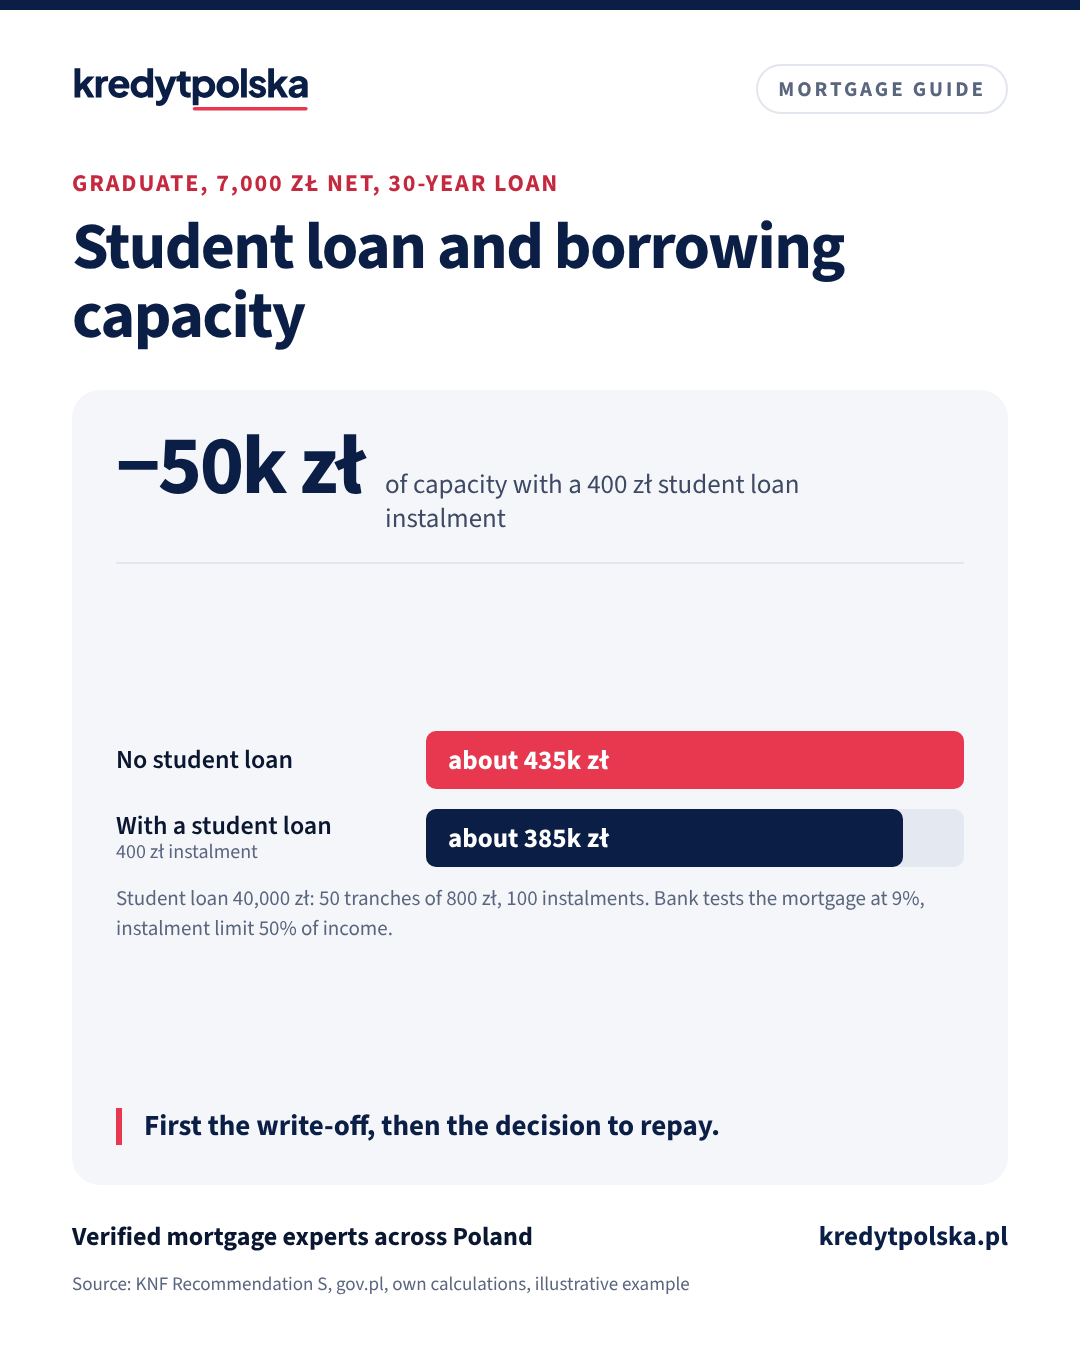
A student loan does not rule out a mortgage, and repaying it on time builds a good credit history in BIK. The bank does, however, deduct its instalment from your income. After 5 years of study with a monthly tranche of 800 zł, the balance is 40,000 zł and the instalment about 400 zł plus interest. For a graduate earning 7,000 zł net this lowers capacity from about 435,000 zł to 385,000 zł. Repaying it before applying pays off when capacity is the limit and enough down payment is left afterwards. If you graduate among the best 10%, apply for forgiveness first: it covers only the part you have not repaid yet.
How the Polish student loan works
The preferential student loan is paid in monthly tranches of 400, 600, 800 or 1,000 zł, for 10 months a year. Repayment starts 2 years after graduation, and there are twice as many instalments as tranches paid. The state covers part of the interest from the Student Loan Fund, so it is one of the cheapest loans you can have. Example: 5 years of study at 800 zł means 50 tranches and 40,000 zł to repay in 100 instalments, about 400 zł a month plus interest.
How a bank counts it
For a bank a student loan is a liability like any other. It appears in the BIK credit report, and the bank deducts the instalment from the part of income that loans may take, usually 40% or 50% of net income under KNF Recommendation S. During the 2-year grace period you pay nothing yet, but the loan is already in BIK: some banks count the future instalment from the schedule, others wait until repayment starts. Attach the agreement or schedule to your application. A student loan or similar debt from another country will not show in BIK, but you must declare it, because banks ask about all your liabilities.
Example: a graduate earning 7,000 zł net
Without other loans, capacity for 30 years is about 435,000 zł. With a student loan instalment of 400 zł it is about 385,000 zł. With 100,000 zł of savings, keeping the student loan allows a home of up to about 485,000 zł; repaying 40,000 zł first allows about 495,000 zł, but the down payment drops to 12% of the price. Below 20% banks usually add low down payment insurance or a higher margin.
Repay first or not
- Repay if capacity is not enough, only a few instalments are left, or you still keep at least 20% down payment and money for purchase costs.
- Keep it if your capacity already covers the home you want, or repaying would eat into your down payment. The bank counts the instalment, not the balance, and the student loan is cheap.
- Forgiveness first: graduates in the best 1% can have 50% forgiven, 1.01–5% get 35% and 5.01–10% get 20%, but only of the amount not yet repaid on the day of the application. Apply at the lending bank, no earlier than 60 days before repayment starts.
The full description in Polish, with tables: Kredyt studencki a kredyt hipoteczny.
| Option | Deposit | Loan | Flat up to |
|---|---|---|---|
| Keeps the student loan | 100,000 zł | about 385k zł | about 485k zł |
| Repays the student loan | 60,000 zł | about 435k zł | about 495k zł |
30-year loan, 9% stress test, instalment limit 50% of income. Without purchase costs. LTV 79% and 88%.
| Instalments left | To repay | Capacity per 1 zł repaid |
|---|---|---|
| 100 | 40,000 zł | about 1.2 zł |
| 60 | 24,000 zł | about 2.1 zł |
| 24 | 9,600 zł | about 5.2 zł |
Instalment 400 zł; repaying it gives back about 50k zł of capacity. Student loan interest not included.
Frequently asked questions
Does a student loan lower mortgage capacity in Poland?
Yes. The bank deducts its instalment from your income like any loan instalment. With an instalment of 400 zł, a graduate earning 7,000 zł net can borrow about 50,000 zł less over 30 years.
Should I repay my student loan before applying for a mortgage?
It pays off when capacity is too low, few instalments are left or you keep enough down payment afterwards. If your capacity is enough, keep the cheap student loan and use the money as a down payment.
Can I get student loan forgiveness after repaying it?
Not for the repaid part. Forgiveness for the best graduates covers only the amount outstanding on the day of the application, so apply before repaying.
Sources
- PKO Bank Polski: preferential student loan, academic year 2026/2027 (Polish)
- Ministry of Science: student loan forgiveness rules (Polish, read 1 November 2026)
- Act on higher education and science, art. 102 (ISAP, Polish)
- Polish Financial Supervision Authority (KNF): Recommendation S on mortgage lending
This guide describes general rules and typical bank practice as of October 2026. Details
It is not legal or tax advice and not a bank offer. Each bank sets its own criteria, and the lending decision is always made by the bank.
Read next
Mortgage calculator for Poland: your monthly instalment
Mortgage calculator for foreigners buying in Poland: equal or decreasing instalments in złoty, total interest, LTV, the bank stress test and a year-by-year schedule.
No credit history in BIK: how to build it before applying for a mortgage in Poland
New to Poland or never had a loan? What an empty BIK report means for a Polish mortgage, what builds credit history (credit card, overdraft, instalments), how long it takes and what to avoid.
Bonuses, overtime and shift pay: how much does a Polish bank count?
How Polish banks treat monthly, quarterly and annual bonuses, the 13th salary, overtime and shift or night allowances when they calculate borrowing capacity, and how to document them.
Foster family or adoption and a mortgage in Poland: what the bank counts
Can a foster family get a mortgage in Poland? How banks treat the pay of a professional foster family, the child allowance and the 800 zł supplement, how a child affects capacity and what adoption changes in the RKM programme.
Arrears with ZUS or the tax office: can you still get a mortgage in Poland?
Can you get a mortgage in Poland with unpaid ZUS contributions or tax arrears? How instalment plans and deferrals affect the certificate of no arrears, compulsory mortgages and what to do before you apply.
Mortgage for PhD students in Poland: does the bank count the doctoral stipend?
How Polish banks treat the doctoral stipend (stypendium doktoranckie) in a mortgage application, how much it is in 2026 and what helps a PhD student get a loan.
Mortgage in Poland on a management contract or a board appointment: how banks count your income
How Polish banks assess income from a management contract (kontrakt menedżerski) or a board appointment (powołanie): tax form, term and dismissal, invoicing through your own company and documents.